
Williams Companies (WMB): Evaluating Valuation After Analyst Praise of Its Natural Gas Advantage
Williams Companies (NYSE:WMB) has landed in the investment spotlight following fresh analyst commentary emphasizing its advantages in today’s natural gas market. The company’s stable cash flows and large pipeline network are drawing renewed attention amid these macro shifts.
See our latest analysis for Williams Companies.
While Williams Companies hasn’t made splashy headlines lately, its steady profile has appealed to investors as the energy market shifts. The stock’s momentum has been quietly building, reflected in a solid 1-year total shareholder return of 38%. This performance highlights both the company’s dependable operations and investor confidence in its long-term prospects, especially as demand for natural gas infrastructure remains robust.
If stable performers like Williams Companies have caught your attention, you may want to broaden your horizons and discover fast growing stocks with high insider ownership.
But with shares up nearly 38% over the past year and trading just below analyst price targets, the question for investors becomes whether Williams Companies is now undervalued or if its resilient outlook is already fully reflected in the stock price. Is there still a buying opportunity, or has the market priced in future growth?
Most Popular Narrative: 2.1% Undervalued
Williams Companies’ narrative fair value stands at $65.41, which is modestly higher than its last close of $64.06. This difference sets the tone for an active debate about how much future growth is priced in today.
Large-scale expansions of Williams’ pipeline network, particularly in high-growth regions like the Haynesville, Gulf Coast, and Transco corridor, are underway or have recently been placed in service to meet surging power, LNG export, and data center demand. This indicates significant volume and revenue growth is expected to accelerate in 2025 and beyond.
Want an inside view of what’s fueling this premium price? The backstory is all about outsized ambitions for future volumes, expanding profit margins, and a bold profit projection that rivals fast-growing industries. There is a key number for future earnings that might catch you off guard. Dive in to see how these expectations shape the valuation.
Result: Fair Value of $65.41 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, shifts in decarbonization policies or unexpected project delays could challenge Williams Companies’ bullish outlook and affect its long-term growth story.
Find out about the key risks to this Williams Companies narrative.
Another View: Market Ratios Suggest a Premium
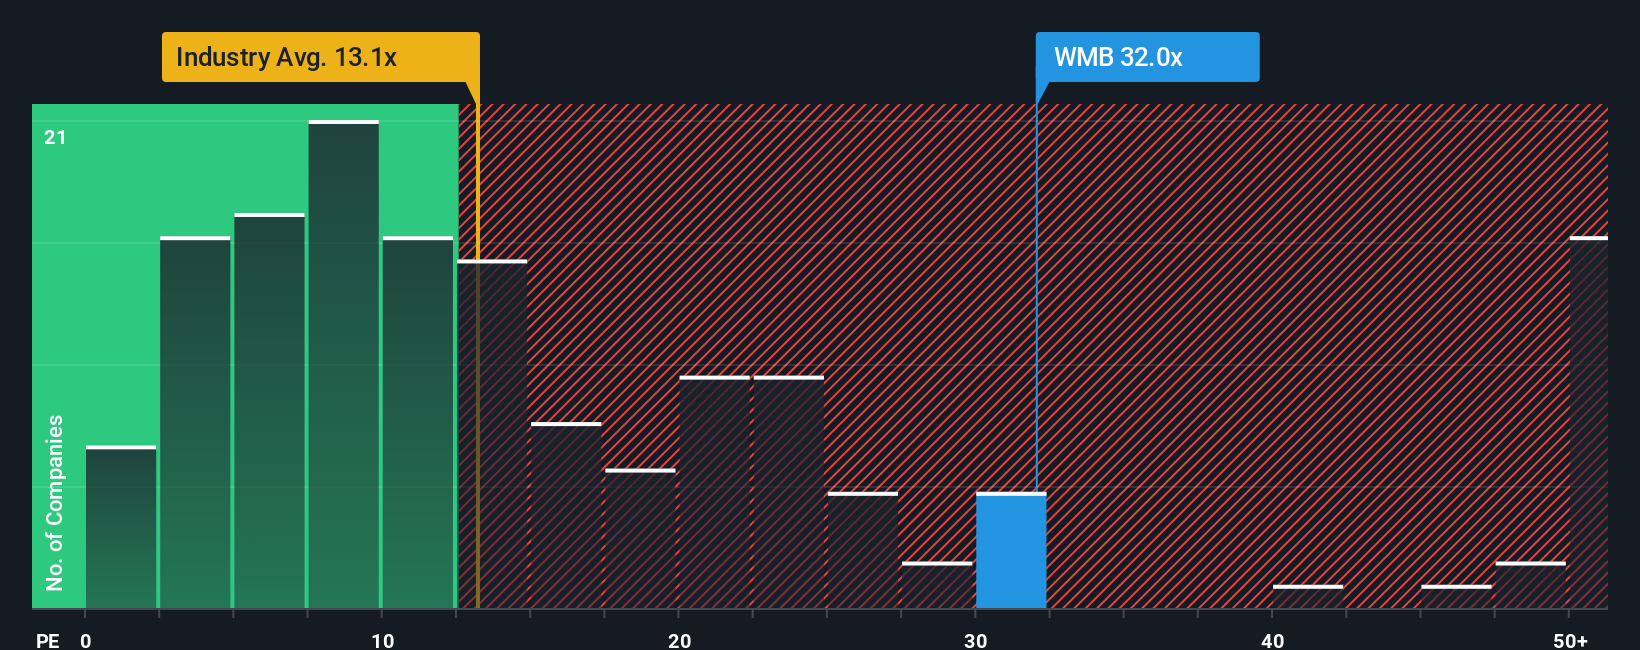
While fair value models suggest Williams Companies has a little room to run, traditional market ratios tell a different story. Shares trade at a price-to-earnings ratio of 32.2x, much higher than the peer average of 14.9x and well above the fair ratio of 20.4x. This signals the stock commands a premium, but it also raises the risk if growth falls short of high expectations. Could the valuation catch up if momentum slows, or is the market betting on something more?
See what the numbers say about this price — find out in our valuation breakdown.
Build Your Own Williams Companies Narrative
If you see things differently or want a firsthand look at the numbers, you can build your own story in just a few short minutes. Do it your way.
A great starting point for your Williams Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
Looking for more investment ideas?
Step up your investment strategy and find your next great stock before the crowd does. Don’t leave opportunity on the table. These exclusive lists help you spot strong performers you might otherwise miss.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Williams Companies might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com