
Should Income Investors Look At Tamar Petroleum Ltd (TLV:TMRP) Before Its Ex-Dividend?
Tamar Petroleum Ltd (TLV:TMRP) stock is about to trade ex-dividend in 3 days. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company’s books as a shareholder in order to receive the dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn’t show on the record date. In other words, investors can purchase Tamar Petroleum’s shares before the 31st of March in order to be eligible for the dividend, which will be paid on the 10th of April.
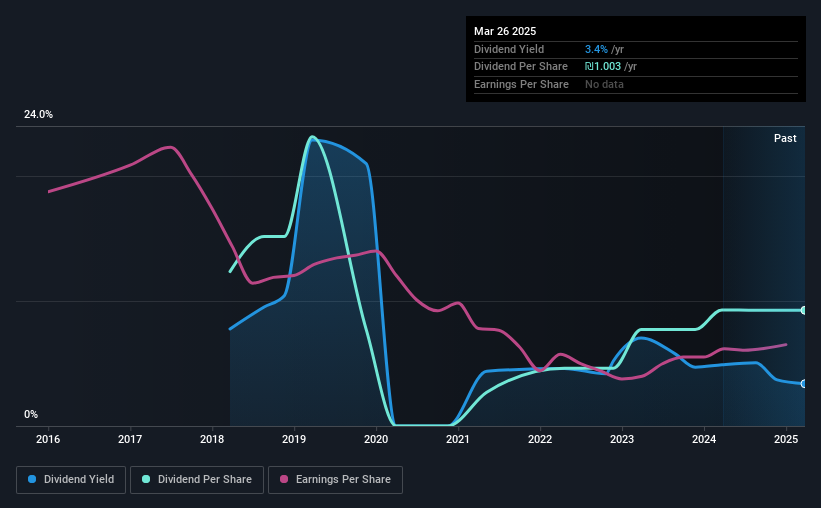
The company’s upcoming dividend is US$0.1692 a share, following on from the last 12 months, when the company distributed a total of US$0.27 per share to shareholders. Last year’s total dividend payments show that Tamar Petroleum has a trailing yield of 3.4% on the current share price of ₪29.65. We love seeing companies pay a dividend, but it’s also important to be sure that laying the golden eggs isn’t going to kill our golden goose! So we need to check whether the dividend payments are covered, and if earnings are growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable — hardly an ideal situation. Fortunately Tamar Petroleum’s payout ratio is modest, at just 43% of profit. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. Thankfully its dividend payments took up just 27% of the free cash flow it generated, which is a comfortable payout ratio.
It’s positive to see that Tamar Petroleum’s dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
View our latest analysis for Tamar Petroleum
Click here to see how much of its profit Tamar Petroleum paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
When earnings decline, dividend companies become much harder to analyse and own safely. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. Readers will understand then, why we’re concerned to see Tamar Petroleum’s earnings per share have dropped 14% a year over the past five years. Ultimately, when earnings per share decline, the size of the pie from which dividends can be paid, shrinks.
The main way most investors will assess a company’s dividend prospects is by checking the historical rate of dividend growth. Tamar Petroleum has seen its dividend decline 4.0% per annum on average over the past seven years, which is not great to see. While it’s not great that earnings and dividends per share have fallen in recent years, we’re encouraged by the fact that management has trimmed the dividend rather than risk over-committing the company in a risky attempt to maintain yields to shareholders.
Final Takeaway
Should investors buy Tamar Petroleum for the upcoming dividend? Tamar Petroleum has comfortably low cash and profit payout ratios, which may mean the dividend is sustainable even in the face of a sharp decline in earnings per share. Still, we consider declining earnings to be a warning sign. Overall, it’s hard to get excited about Tamar Petroleum from a dividend perspective.
While it’s tempting to invest in Tamar Petroleum for the dividends alone, you should always be mindful of the risks involved. Our analysis shows 3 warning signs for Tamar Petroleum that we strongly recommend you have a look at before investing in the company.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Valuation is complex, but we’re here to simplify it.
Discover if Tamar Petroleum might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.