
Should HASI’s Strong Revenue Beat From Climate Investments Prompt Action From HA Sustainable Infrastructure Capital (HASI) Investors?
- HA Sustainable Infrastructure Capital recently reported a strong second quarter, with revenues surpassing analyst expectations by 32.1% due to its investments in climate-positive infrastructure projects.
- This performance highlights how the company’s focus on sustainable infrastructure is playing a central role in driving revenue growth beyond market forecasts.
- We’ll now explore how HA Sustainable Infrastructure Capital’s climate-positive investments are shaping its current investment narrative.
Explore 24 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
What Is HA Sustainable Infrastructure Capital’s Investment Narrative?
To be a shareholder in HA Sustainable Infrastructure Capital, you need to believe in the broader shift toward climate-focused infrastructure investment and its potential to outpace market growth. The recent news of second quarter revenues coming in over 32% above analyst expectations adds positive momentum and may prompt a near-term re-evaluation of both growth catalysts and perceived risks. While the market had previously flagged slow earnings growth, high debt levels and dividend sustainability as top issues, the solid revenue signal could help address some uncertainty in the short term, though it does not fully remove questions about funding costs or dividend coverage. With leadership changes still fresh and balance sheet quality under scrutiny, the recent beat is material and could shift sentiment around the company’s projected growth and valuation, particularly if sustained in future quarters.
Yet despite these gains, the quality of earnings coverage for the dividend remains a key concern that investors should be aware of. Despite retreating, HA Sustainable Infrastructure Capital’s shares might still be trading 13% above their fair value. Discover the potential downside here.
Exploring Other Perspectives
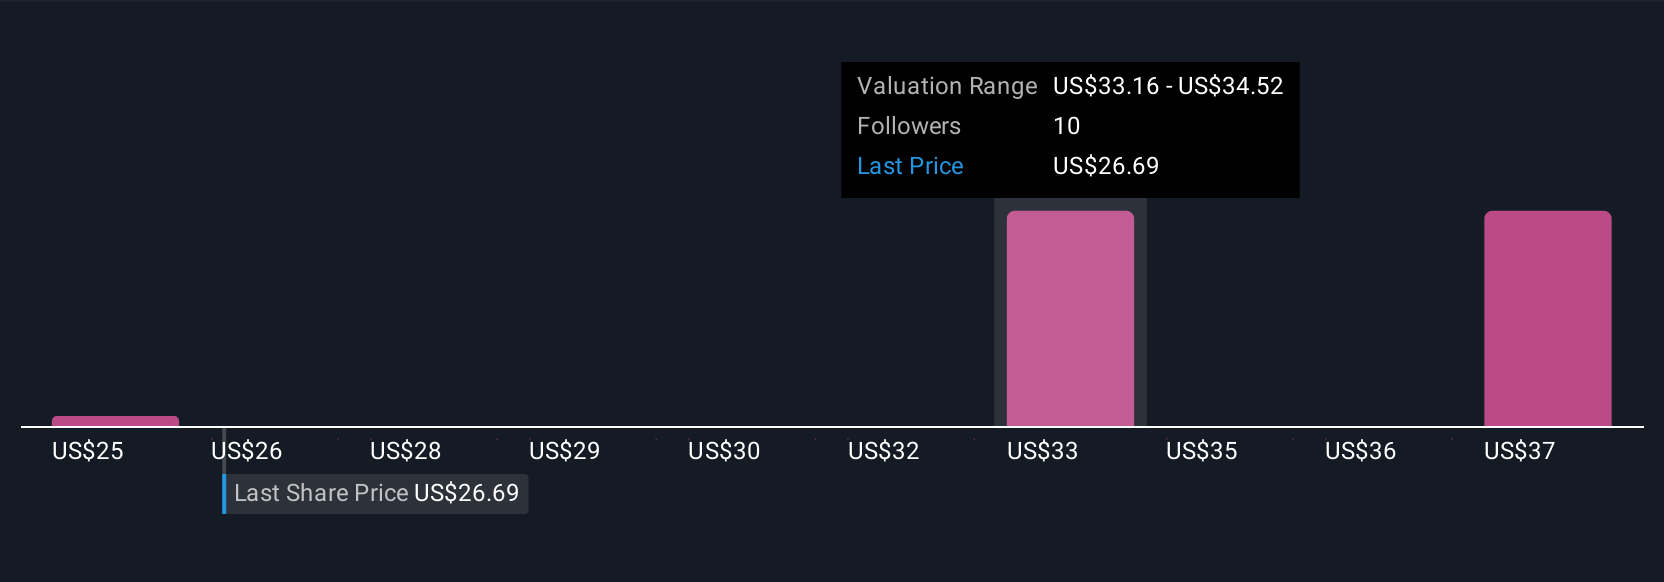
Four individual fair value estimates from the Simply Wall St Community currently range from US$24.24 to US$39.29 per share, revealing a broad spectrum of investor opinion. While optimism around revenue growth is evident after the recent results, questions remain about how consistent performance will factor into future returns. See how your outlook compares with this variety of perspectives.
Explore 4 other fair value estimates on HA Sustainable Infrastructure Capital — why the stock might be worth as much as 41% more than the current price!
Build Your Own HA Sustainable Infrastructure Capital Narrative
Disagree with this assessment? Create your own narrative in under 3 minutes — extraordinary investment returns rarely come from following the herd.
No Opportunity In HA Sustainable Infrastructure Capital?
Our daily scans reveal stocks with breakout potential. Don’t miss this chance:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if HA Sustainable Infrastructure Capital might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com