
Occidental Petroleum (OXY) Valuation Check As New Carbon Removal Deal Underscores Growing Carbon Management Ambitions
Occidental Petroleum (OXY) is back in focus after its carbon capture subsidiary, 1PointFive, agreed to sell 9,000 metric tons of Direct Air Capture carbon removal credits to Bain & Company over a three-year period.
See our latest analysis for Occidental Petroleum.
That 1PointFive deal lands at a time when interest in Occidental’s carbon management story is building again, with a 7 day share price return of 8.12% and a 30 day share price return of 10.28%, even though the 1 year total shareholder return is a 14.05% decline and the 3 year total shareholder return is a 27.70% decline, while the 5 year total shareholder return of 104.32% shows how volatile the journey has been.
If this kind of transition story has your attention, it could be a good moment to look across the energy value chain, including aerospace and defense stocks for companies exposed to long term security and infrastructure themes.
With Occidental trading at US$44.32 and sitting about 12% below the average analyst price target, along with an indicated intrinsic discount of roughly 66%, you have to ask: is this a genuine opportunity or is the market already pricing in future growth?
Most Popular Narrative: 10.7% Undervalued
Against a last close of US$44.32, the most followed narrative points to a fair value around US$49.63, putting the current setup into sharper focus.
The company’s accelerated expansion and commercialization of carbon capture, including imminent operational start of the STRATOS Direct Air Capture facility and newly contracted CDR volumes through 2030, positions Occidental to monetize carbon management via government incentives (e.g., 45Q credits) and growing CDR demand, supporting incremental, high-margin revenue and improved net margins.
Curious how modest top line expectations still support a higher fair value? The narrative leans heavily on margin expansion and future earnings multiples. The tension between cautious revenue assumptions and richer profitability is what really drives the model.
Result: Fair Value of $49.63 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, you still need to weigh real risks, including sensitivity to oil prices and the execution and policy uncertainty around large scale carbon capture projects.
Find out about the key risks to this Occidental Petroleum narrative.
Another Take: Multiples Paint a Tougher Picture
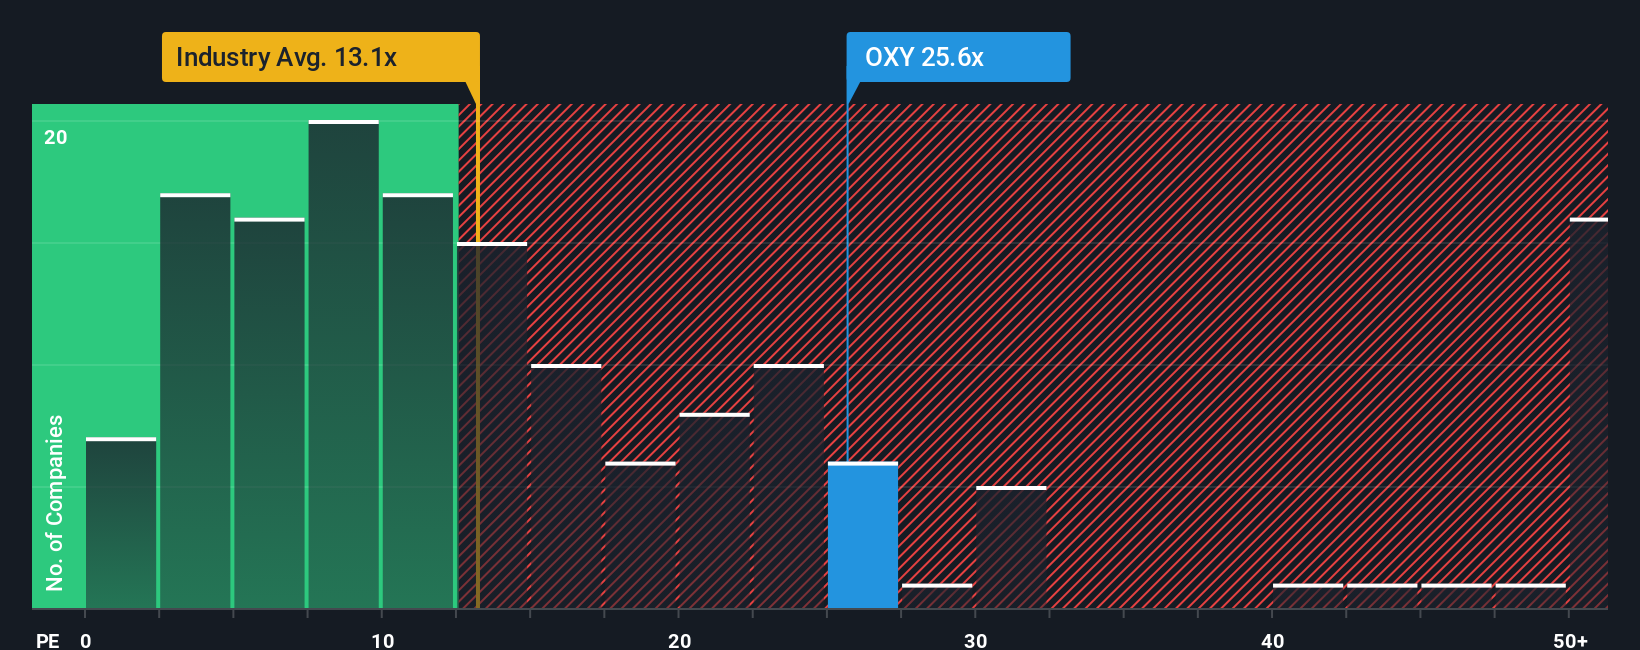
Before you lean too hard on that 10.7% undervaluation story, it is worth looking at what you are actually paying today. Occidental trades on a P/E of 29.9x, compared with a fair ratio of 20.7x, the US Oil and Gas industry at 13.7x, and peers at 22x.
That gap signals you are paying a richer price than both the sector and similar companies, while also sitting above the fair ratio the market could move toward over time. The question is whether Occidental’s carbon and earnings story is strong enough for you to stay comfortable with that premium.
See what the numbers say about this price — find out in our valuation breakdown.
Build Your Own Occidental Petroleum Narrative
If you see the data differently or simply prefer to test your own assumptions, you can build a custom thesis in just a few minutes: Do it your way.
A great starting point for your Occidental Petroleum research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
Ready to Find Your Next Idea?
If Occidental has you thinking about what to own next, do not stop here. Use focused stock lists to quickly surface ideas that fit your style.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com