
Occidental Petroleum (OXY) Valuation Check After Recent Share Price Rebound And Mixed Longer Term Returns
Context for Occidental Petroleum (OXY) after Recent Moves
Occidental Petroleum (OXY) has drawn renewed attention after a recent price move that leaves the shares around $46.31, with performance numbers that look quite different over the past month, year and 3 years.
For you as an investor, the mix of shorter term gains and longer term volatility can raise questions about how the current share price lines up with the company’s fundamentals, especially given its diverse operations across oil and gas, chemicals and midstream services.
See our latest analysis for Occidental Petroleum.
Recent trading has been relatively firm, with a 1 month share price return of 8.05% and a 3 month share price return of 10.79%. However, the 3 year total shareholder return of a 25.84% decline shows that momentum has only more recently picked up around the current US$46.31 level.
If OXY’s rebound has you thinking about where else capital might be moving in the energy space, it could be a good time to scan 87 nuclear energy infrastructure stocks as another way to source ideas.
With OXY trading at about $46.31, sitting on an intrinsic discount figure of 64.80% and only a small gap to the average analyst target, is the stock still underappreciated, or is the market already pricing in future growth?
Most Popular Narrative: 32.2% Undervalued
According to the most followed narrative on Occidental Petroleum, a fair value of $68.29 sits well above the recent $46.31 share price, which raises questions about what is built into those assumptions.
Occidental’s current value is shaped by a combination of lessons learned from past mistakes and recent bold strategic moves. The OxyChem sale and CrownRock acquisition together reflect a shift toward a more focused, higher quality asset base in the Permian, underpinned by balance sheet repair and a closer alignment with its largest shareholder, Berkshire Hathaway.
Curious what kind of production runway, margin profile, and long term cash flow pattern are baked into that $68.29 figure? The narrative leans heavily on specific assumptions about Permian inventory quality, future profitability from low carbon ventures, and how earnings might trend relative to traditional oil peers, without spelling those inputs out in the headline number.
Result: Fair Value of $68.29 (UNDERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, this story can quickly look different if Direct Air Capture costs stay high, or if lower quality shale inventory starts to weigh on returns and required spending.
Find out about the key risks to this Occidental Petroleum narrative.
Another View: Earnings Multiple Tells a Different Story
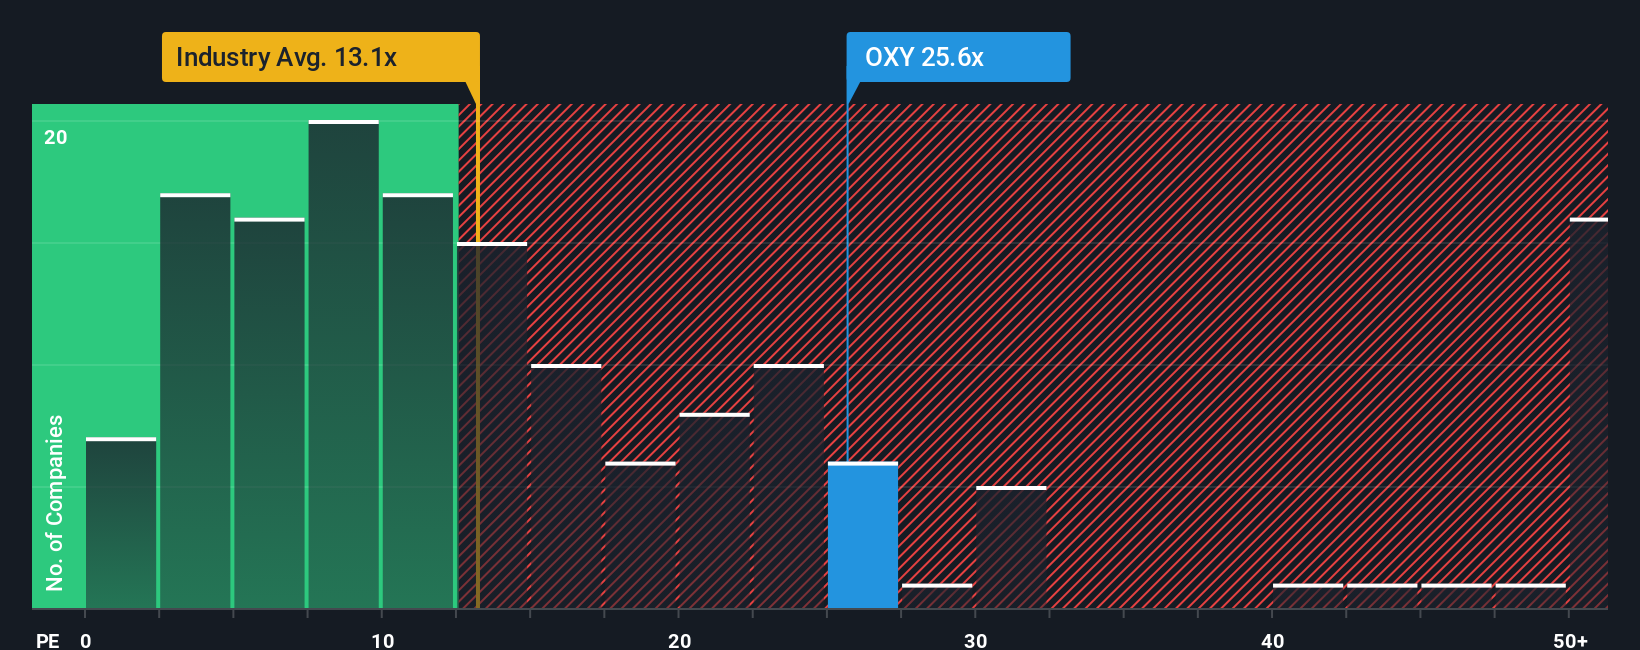
That 32.2% undervaluation story sits uncomfortably next to how the market is actually pricing Occidental today. On a P/E of 31.3x, the shares trade well above the US Oil and Gas industry at 14.1x, peers at 23.4x, and our fair ratio of 22.5x. In plain terms, you are paying a premium price for a company that our own checks flag as trading above its fair ratio, even though the DCF suggests upside. Is this a case of the cash flow model being too generous, or the market already baking in a lot of optimism?
See what the numbers say about this price — find out in our valuation breakdown.
Build Your Own Occidental Petroleum Narrative
If parts of this story do not sit right with you or you simply prefer to lean on your own judgement, you can test the assumptions, tweak the inputs, and shape a thesis that fits your view in just a few minutes, then Do it your way.
A great starting point for your Occidental Petroleum research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
Looking for more investment ideas?
If you are weighing what to do next after reviewing Occidental Petroleum, now is the moment to widen your watchlist using focused idea lists built from our screeners.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com