
Is Occidental Petroleum (OXY) Pricing Reflect Recent Oil Volatility Or A Potential Opportunity?
- If you are wondering whether Occidental Petroleum is a bargain or just fairly priced at its recent US$42.70 close, you are not alone.
- The stock has had mixed returns, with a 5.1% gain over the last 30 days, a 0.8% return year to date, a 16.0% decline over 1 year, and a 32.9% decline over 3 years, while still sitting 110.9% above its level 5 years ago.
- Recent news coverage has focused on Occidental Petroleum as a major US energy name, often discussed in the context of oil price moves, capital allocation decisions, and its role among large listed producers. This backdrop helps frame why the share price has seen periods of renewed interest as well as pullbacks.
- Our valuation checks currently give Occidental Petroleum a valuation score of 2 out of 6. This sets up a closer look at how different methods assess the stock today and hints at an even more rounded way to think about value that we will come to by the end of this article.
Occidental Petroleum scores just 2/6 on our valuation checks. See what other red flags we found in the full valuation breakdown.
Approach 1: Occidental Petroleum Discounted Cash Flow (DCF) Analysis
A Discounted Cash Flow, or DCF, model estimates what a business could be worth today by projecting its future cash flows and then discounting those back to a present value. For Occidental Petroleum, the model used is a 2 Stage Free Cash Flow to Equity approach, which focuses on the cash available to shareholders after all expenses and investments.
The latest twelve month free cash flow is about $4.40b. Analyst based projections and Simply Wall St extrapolations indicate free cash flow reaching around $5.43b by 2030, with a series of annual estimates between 2026 and 2035 that are discounted back using this DCF framework. All cash flows here are expressed in US$.
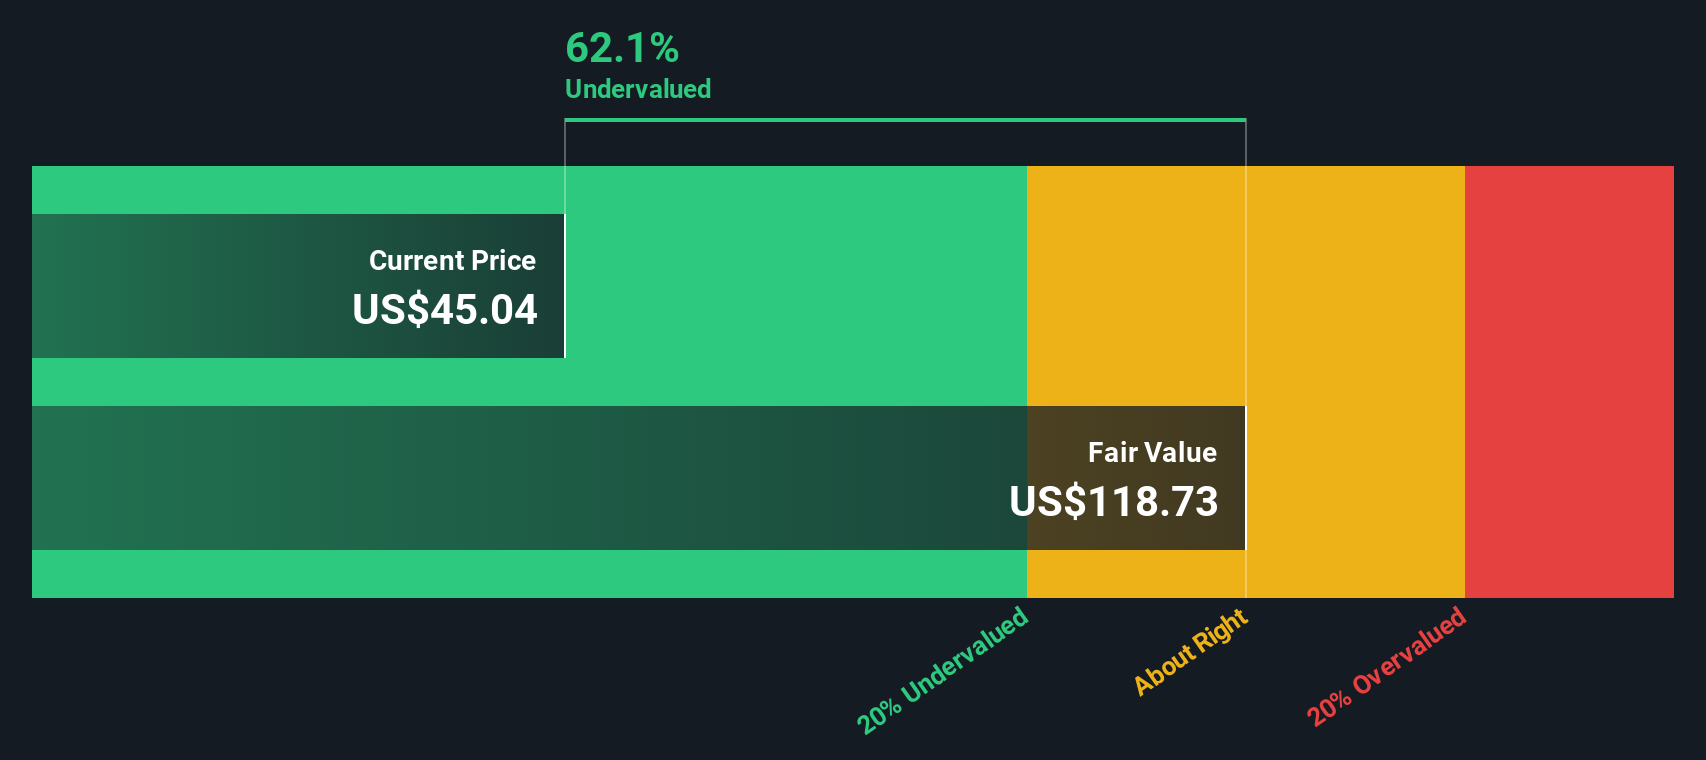
On this basis, the DCF model arrives at an estimated intrinsic value of about $129.59 per share. Compared with the recent share price of roughly $42.70, this implies a 67.1% discount, which indicates that the shares are trading well below this model’s estimate of fair value.
Result: UNDERVALUED
Our Discounted Cash Flow (DCF) analysis suggests Occidental Petroleum is undervalued by 67.1%. Track this in your watchlist or portfolio, or discover 863 more undervalued stocks based on cash flows.
Approach 2: Occidental Petroleum Price vs Earnings
For a profitable company like Occidental Petroleum, the P/E ratio is a useful way to think about what you are paying for each dollar of current earnings. Investors usually accept a higher P/E when they expect stronger growth or see lower risk, and a lower P/E when they expect slower growth or see higher risk.
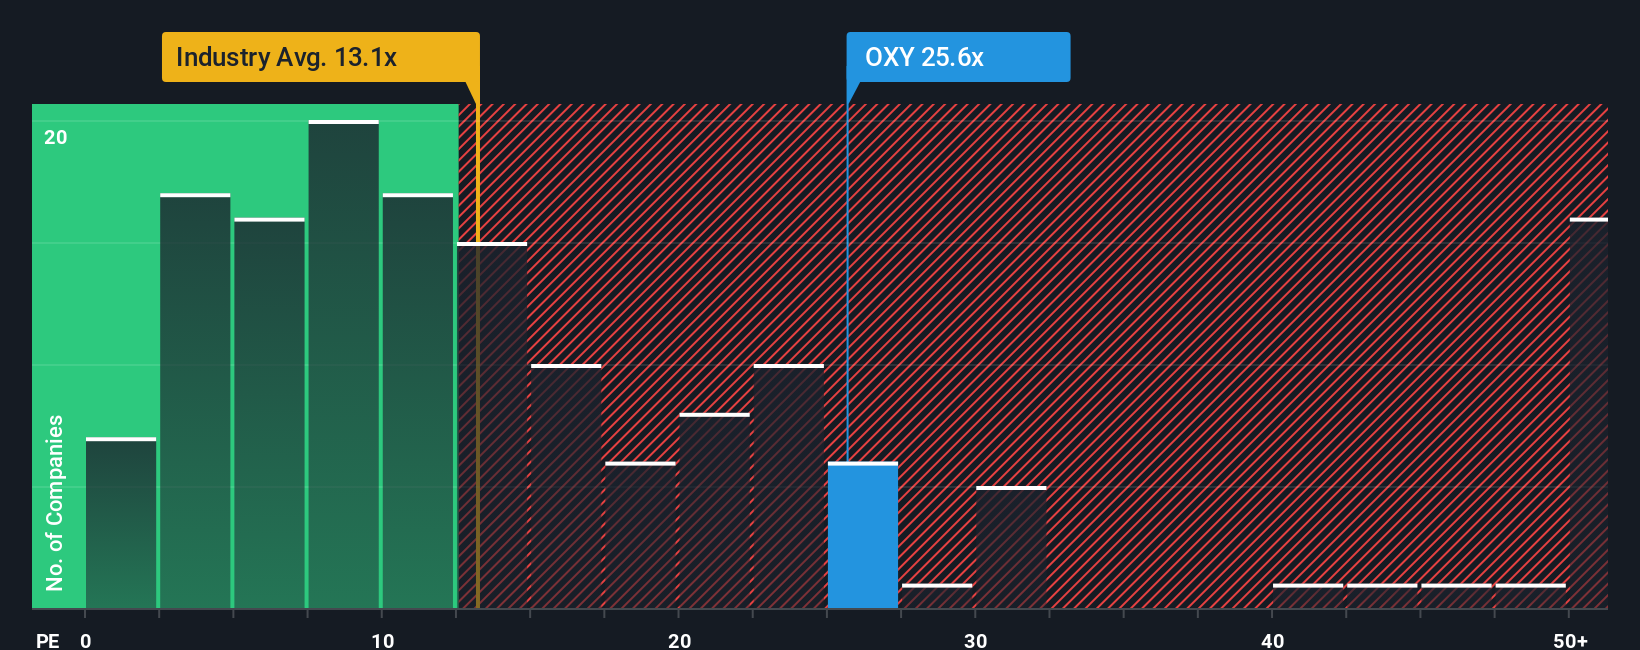
Occidental currently trades on a P/E of 28.81x. That sits above the broader Oil and Gas industry average P/E of 13.71x and also above the peer group average of 21.87x. On the surface, that suggests the market is assigning a richer earnings multiple to Occidental than to many of its industry peers.
Simply Wall St’s Fair Ratio framework goes a step further. It estimates what P/E might be reasonable given factors such as the company’s earnings growth profile, industry, profit margins, market cap and specific risk characteristics. This tailored view can be more informative than a simple peer or industry comparison because it adjusts for differences in quality and risk between companies. For Occidental, the Fair Ratio is 20.64x, which is below the current P/E of 28.81x, indicating the shares are pricing in more than this model would suggest.
Result: OVERVALUED
P/E ratios tell one story, but what if the real opportunity lies elsewhere? Discover 1445 companies where insiders are betting big on explosive growth.
Upgrade Your Decision Making: Choose your Occidental Petroleum Narrative
Earlier we mentioned that there is an even better way to understand valuation, so let us introduce you to Narratives, a simple way for you to attach a clear story about Occidental Petroleum to the numbers you care about, link that story to a forecast for revenue, earnings and margins, and then see a Fair Value you can compare to the current price.
On Simply Wall St’s Community page, Narratives are available as an easy tool that millions of investors use to set their own assumptions and see how those choices affect Fair Value, which is then updated automatically when new information such as earnings or news is added to the platform.
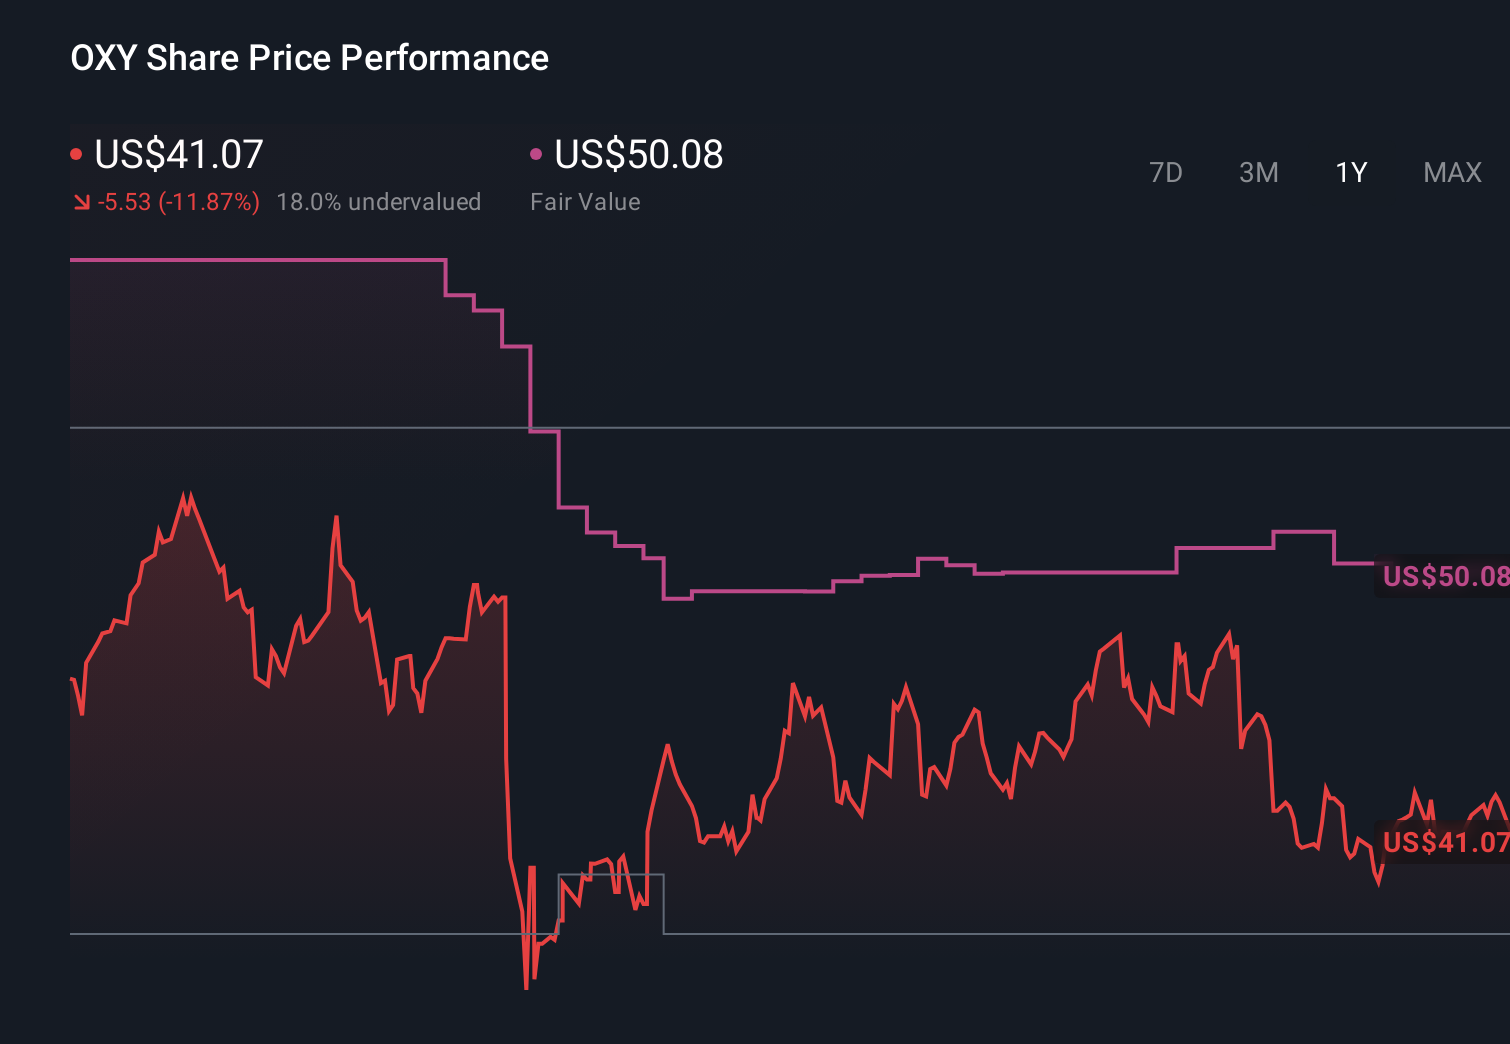
For Occidental, one investor might build a Narrative that leans heavily on carbon capture and storage, and uses assumptions similar to the US$55.05 Fair Value with a 4.0% revenue growth rate, a 16.0% profit margin and a 7.14% discount rate. Another investor might focus more on traditional oil and gas, and use inputs closer to the US$49.63 Fair Value with a 6.63% revenue decline, a 13.87% profit margin and a 7.13% discount rate. Comparing each Narrative’s Fair Value with the current share price can then help inform their own investment decisions.
Do you think there’s more to the story for Occidental Petroleum? Head over to our Community to see what others are saying!
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com