
Is Now the Right Moment for First Solar Stock After 35% Jump in 2025?
- Wondering if First Solar’s recent performance means the stock is a bargain or just riding a wave? You’re in the right place for a closer look at what the numbers (and a bit of context) might really be telling us.
- First Solar’s stock has made some serious moves lately, climbing 35.7% year-to-date and 32.9% over the past year. However, it dipped 5.4% in the past week, which may signal that volatility could be as much an opportunity as a warning sign.
- This past month, First Solar’s price shifts have been set against a backdrop of increased attention on clean energy policy in the US, as well as significant investments in solar infrastructure by major utility providers. Headlines about fresh government incentives and new project announcements have fueled both optimism and speculation around future revenue growth.
- As for value, First Solar currently scores a 5 out of 6 on our valuation checks, which is an impressive mark that’s worth unpacking. We’ll walk through several approaches to valuation, but stick around, because by the end of this article you’ll see there’s an even deeper way to judge if the numbers really stack up.
Find out why First Solar’s 32.9% return over the last year is lagging behind its peers.
Approach 1: First Solar Discounted Cash Flow (DCF) Analysis
The Discounted Cash Flow (DCF) model is a common approach used by analysts to estimate a company’s intrinsic value by projecting its future cash flows and then discounting those amounts back to their present value. This gives investors a sense of what a company’s shares are truly worth, based on fundamental financial performance rather than just market sentiment.
For First Solar, the current Free Cash Flow sits at a negative $22.4 million, reflecting recent investments and spending. However, the DCF model projects strong growth ahead. Analyst forecasts estimate that Free Cash Flow will climb to $1.42 billion in 2026 and keep accelerating, reaching nearly $4.0 billion by 2029. Beyond that, Simply Wall St extrapolates continued increases, with the ten-year forecast topping $5.6 billion in 2035. All figures are in US dollars.
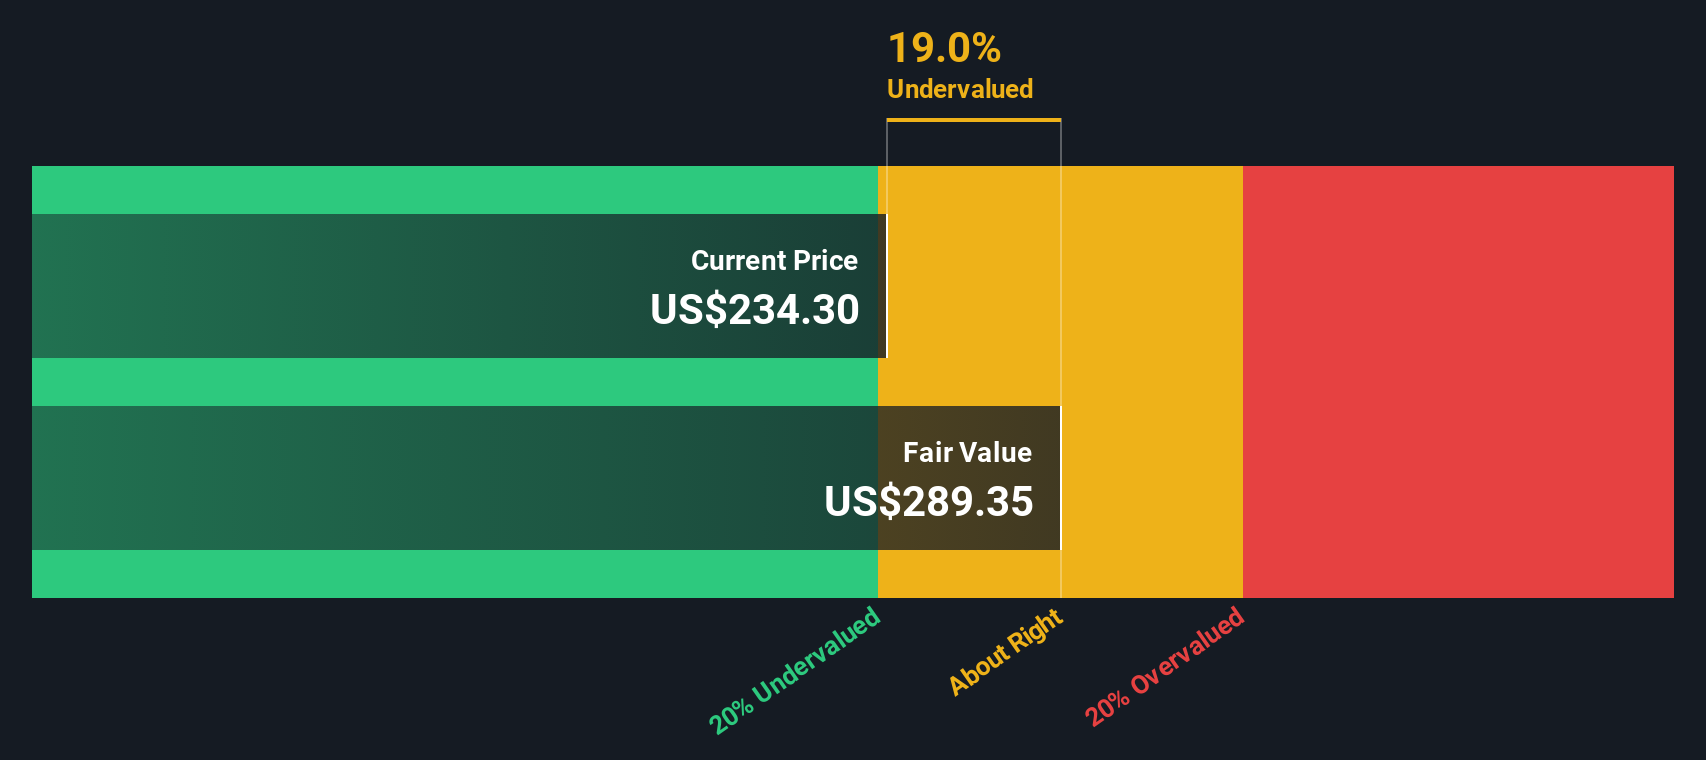
Based on these projections, the resulting intrinsic value for First Solar is estimated at $480 per share. This figure stands about 47.3% higher than the current share price and implies a substantial margin of undervaluation.
Result: UNDERVALUED
Our Discounted Cash Flow (DCF) analysis suggests First Solar is undervalued by 47.3%. Track this in your watchlist or portfolio, or discover 878 more undervalued stocks based on cash flows.
Approach 2: First Solar Price vs Earnings (PE Ratio)
The price-to-earnings (PE) ratio is a widely used valuation metric, especially for profitable companies like First Solar. This ratio tells investors how much they are paying for each dollar of earnings, making it easier to compare companies across industries and historical periods.
The “right” or “fair” PE ratio for a stock depends on factors such as expected earnings growth, profit margins, and perceived risk. Fast-growing or lower-risk companies typically trade at higher PE ratios, while slower-growing or riskier firms tend to command lower multiples.
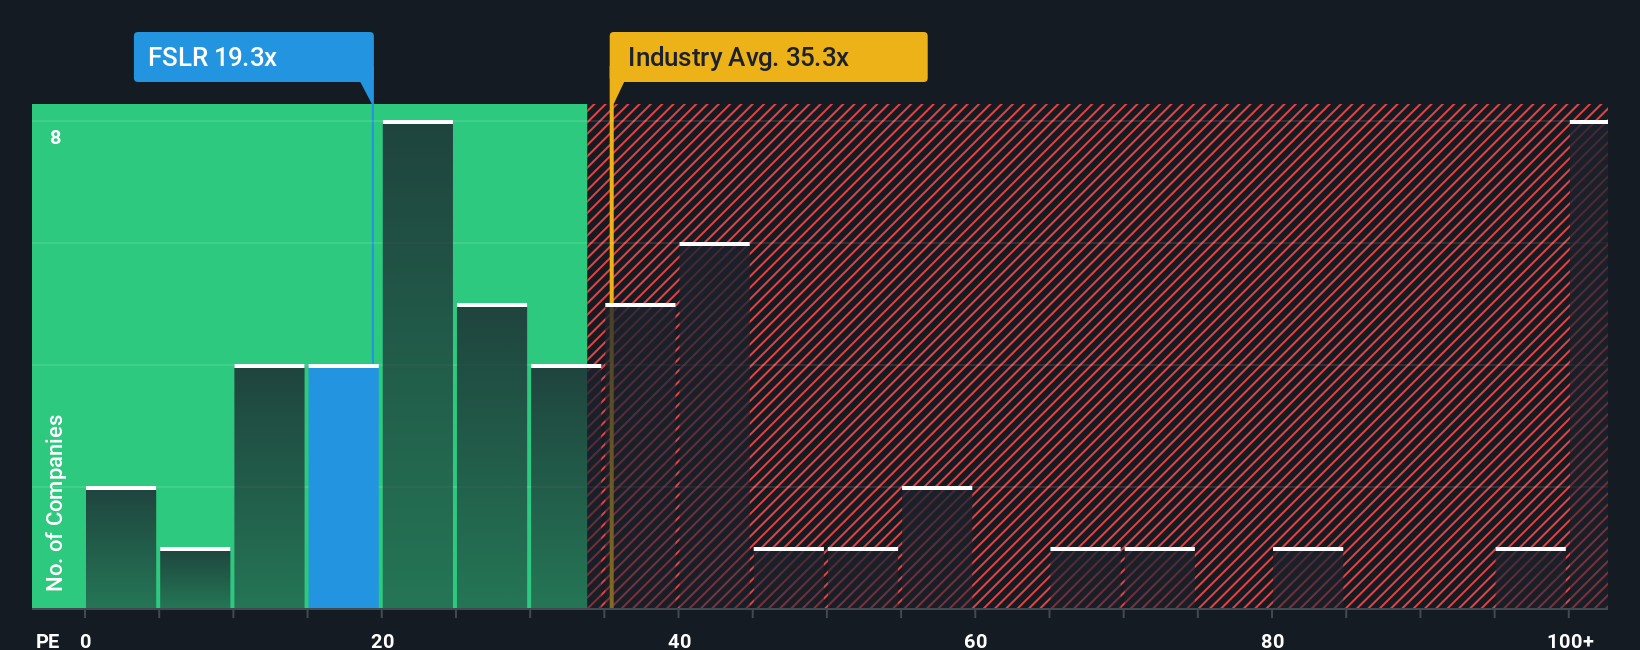
Currently, First Solar trades at a PE ratio of 19.4x. This compares favorably to the average PE across the semiconductor industry, which stands at 34.2x, and to its peer group average of 37.8x. On the surface, this would hint that First Solar is attractively priced relative to these benchmarks.
However, Simply Wall St’s “Fair Ratio” model takes this a step further by incorporating more nuanced data such as projected growth, risk profile, profit margins, and company size. This results in a Fair Ratio of 38.0x for First Solar. Unlike a blunt industry average, the Fair Ratio drills down into what is appropriate given First Solar’s specific fundamentals and prospects.
When comparing the Fair Ratio of 38.0x to the company’s current 19.4x, First Solar looks significantly undervalued on this basis, suggesting the market may not be fully appreciating its earnings power and long-term growth outlook.
Result: UNDERVALUED
PE ratios tell one story, but what if the real opportunity lies elsewhere? Discover 1405 companies where insiders are betting big on explosive growth.
Upgrade Your Decision Making: Choose your First Solar Narrative
Earlier we mentioned there is an even better way to understand valuation, so let’s introduce you to Narratives. This is a smarter, more dynamic approach to making investment decisions. A Narrative is simply your story about a company’s future: it connects your expectations for important numbers like revenue, earnings, and margins to a clear financial forecast and, ultimately, to your fair value estimate.
Unlike traditional models, Narratives help you see beyond the numbers by letting you explain your assumptions and reasoning. On Simply Wall St’s Community page, millions of investors use Narratives to outline their perspectives on a company, map out what they believe is likely to happen, and quickly compare their fair value to the current price to help decide when to buy or sell.
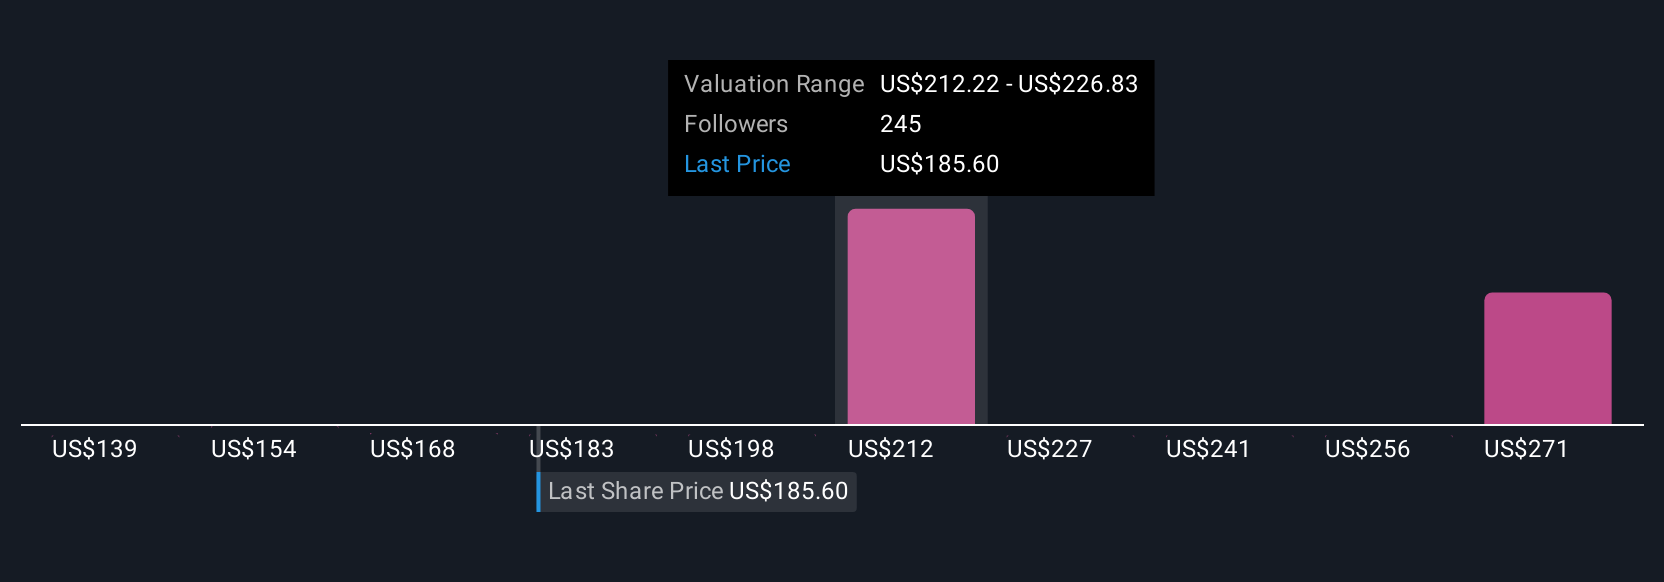
Best of all, Narratives are not static. If new news or earnings arrive, your narrative’s fair value refreshes, keeping your decisions up to date as conditions change. For First Solar, for example, some investors build bullish Narratives driven by optimism around domestic policy, robust backlogs, and innovation, yielding fair values as high as $287 per share. Others, more cautious, cite margin risks and set targets as low as $100. This makes it easier than ever to see how the community’s full spectrum of outlooks stack up against your own.
Do you think there’s more to the story for First Solar? Head over to our Community to see what others are saying!
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com