
A Look At Uranium Energy (UEC) Valuation After Renewed Optimism Around Nuclear Power And Data Center Demand
Uranium Energy (UEC) has been in focus after a sharp move in its share price, driven by expectations of stronger uranium demand tied to AI and cryptocurrency data centers, as well as fresh federal support for nuclear power.
See our latest analysis for Uranium Energy.
That enthusiasm has been reflected in the recent trading pattern, with a 55.12% 1 month share price return and a 36.31% year to date share price return. This has fed into a very large 5 year total shareholder return and signals strong positive momentum.
If you are watching how nuclear linked names are reacting to AI and data center demand, it may also be worth checking out aerospace and defense stocks as another way to source ideas tied to long term infrastructure and security themes.
With UEC now near an all time high and trading slightly above one analyst price target, the key question is whether the recent uranium optimism leaves room for more upside or if the market has already priced in future growth.
Price-to-Book of 6.6x: Is It Justified?
UEC last closed at US$17.87 and is described as expensive on a 6.6x P/B, which sits above both peer and broader industry reference points.
P/B compares the market value of the equity to its book value. A higher ratio often reflects expectations for future asset profitability or growth optionality.
For a company that is currently unprofitable and reporting a net loss of US$77.839m on revenue of US$49.75m, a premium P/B suggests investors are paying up for future uranium exposure rather than current earnings power.
Against the US Oil and Gas industry average P/B of 1.3x and a peer average of 5.2x, UEC’s 6.6x multiple is materially higher. This indicates the market is assigning a richer valuation per dollar of net assets than is typical across the sector.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 6.6x (OVERVALUED)
However, you also have to weigh the recent share price surge against UEC’s current net loss and the possibility that uranium optimism cools or policy support shifts.
Find out about the key risks to this Uranium Energy narrative.
Another View: Our DCF Model Suggests Shares Look Expensive
The SWS DCF model points in the same direction as the high P/B. At US$17.87, Uranium Energy is trading above an estimated fair value of US$12.49, which suggests the shares may be overvalued rather than offering a clear margin of safety at this time.
Look into how the SWS DCF model arrives at its fair value.
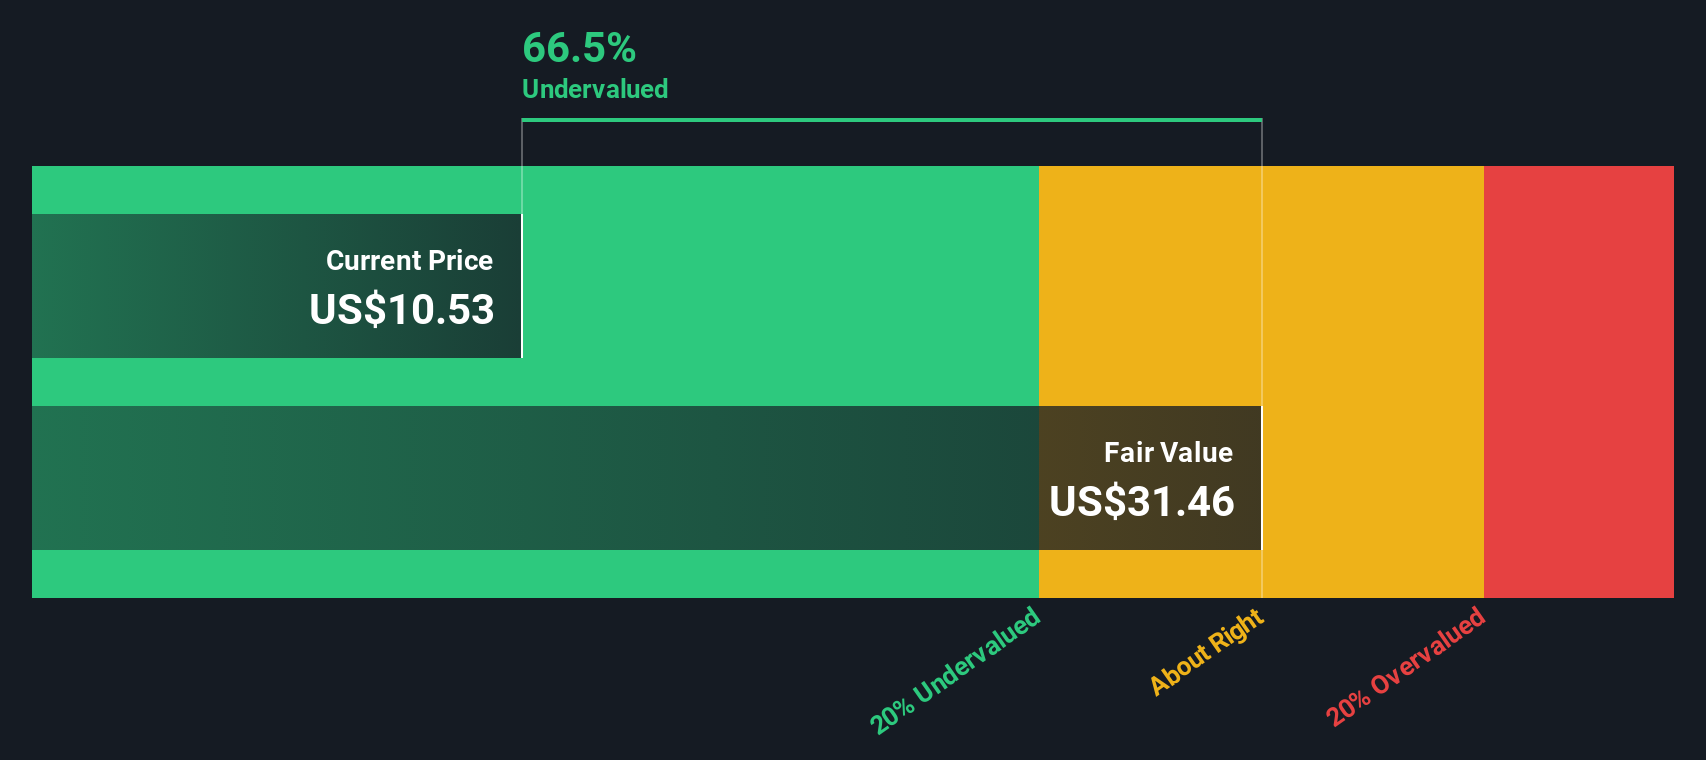
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Uranium Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 863 undervalued stocks based on their cash flows. If you save a screener we even alert you when new companies match — so you never miss a potential opportunity.
Build Your Own Uranium Energy Narrative
If you look at the numbers and come to a different conclusion, or simply prefer to cross check the assumptions yourself, you can build a personalised Uranium Energy story in just a few minutes using Do it your way.
A great starting point for your Uranium Energy research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
Looking for more investment ideas?
If UEC has caught your eye, do not stop there. Cast a wider net with focused stock lists that can surface opportunities you might otherwise miss.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com