
A Look At Occidental Petroleum (OXY) Valuation As Dividend Hike Bets Grow After OxyChem Sale
Occidental Petroleum (OXY) is back in focus as investors look ahead to its February 19 Q4 earnings release, where many expect another dividend increase following the recent US$9.7b OxyChem sale.
See our latest analysis for Occidental Petroleum.
The share price has picked up into earnings, with a 1 day share price return of 3.01% and a 30 day share price return of 8.05%. However, the 1 year total shareholder return of 11.42% and 3 year total shareholder return of 29.13% are still weak compared to the strong 5 year total shareholder return of 124.36%. This suggests that recent momentum is building after a tougher stretch for longer term holders.
If you are weighing how energy names like Occidental Petroleum fit into your portfolio, it can help to compare them with other aerospace and defense stocks that are also closely tied to global commodity and spending cycles.
With Q4 earnings, a potential dividend hike and the US$9.7b OxyChem sale all in play, the key question now is whether OXY is still trading at a discount or if the market already reflects expectations for future growth.
Price-to-Earnings of 29.4x: Is it justified?
Occidental Petroleum closed at US$43.51, and it is trading on a P/E of 29.4x, which is high relative to several valuation checks.
The P/E ratio compares the current share price to earnings per share. A higher multiple usually means the market is pricing in stronger or more resilient profits.
For OXY, the current 29.4x P/E is described as expensive versus the estimated fair P/E of 20.2x. This is a level the market could potentially gravitate toward if expectations cool. It is also described as expensive compared with the US Oil and Gas industry average of 13.5x and the peer average of 22.2x, which signals investors are paying a clear premium to own these earnings.
Explore the SWS fair ratio for Occidental Petroleum
Result: Price-to-Earnings of 29.4x (OVERVALUED)
However, recent 1-year and 3-year total shareholder return declines and an annual revenue contraction of 5.47% could challenge the case for paying a premium multiple.
Find out about the key risks to this Occidental Petroleum narrative.
Another View: Our DCF Model Points to a Large Discount
While the 29.4x P/E looks expensive compared with OXY’s own fair ratio of 20.2x, our DCF model paints a very different picture. It suggests a fair value of US$128.82 per share versus the current US$43.51, which is a 66.2% discount to that estimate.
This gap highlights a real tension for investors. On one side, the earnings multiple looks rich compared with the US Oil and Gas industry and peers. On the other side, the SWS DCF model implies the market may be heavily discounting OXY’s future cash flows. Which signal you lean on depends on how much weight you give to near term earnings compared with long term cash generation.
Look into how the SWS DCF model arrives at its fair value.
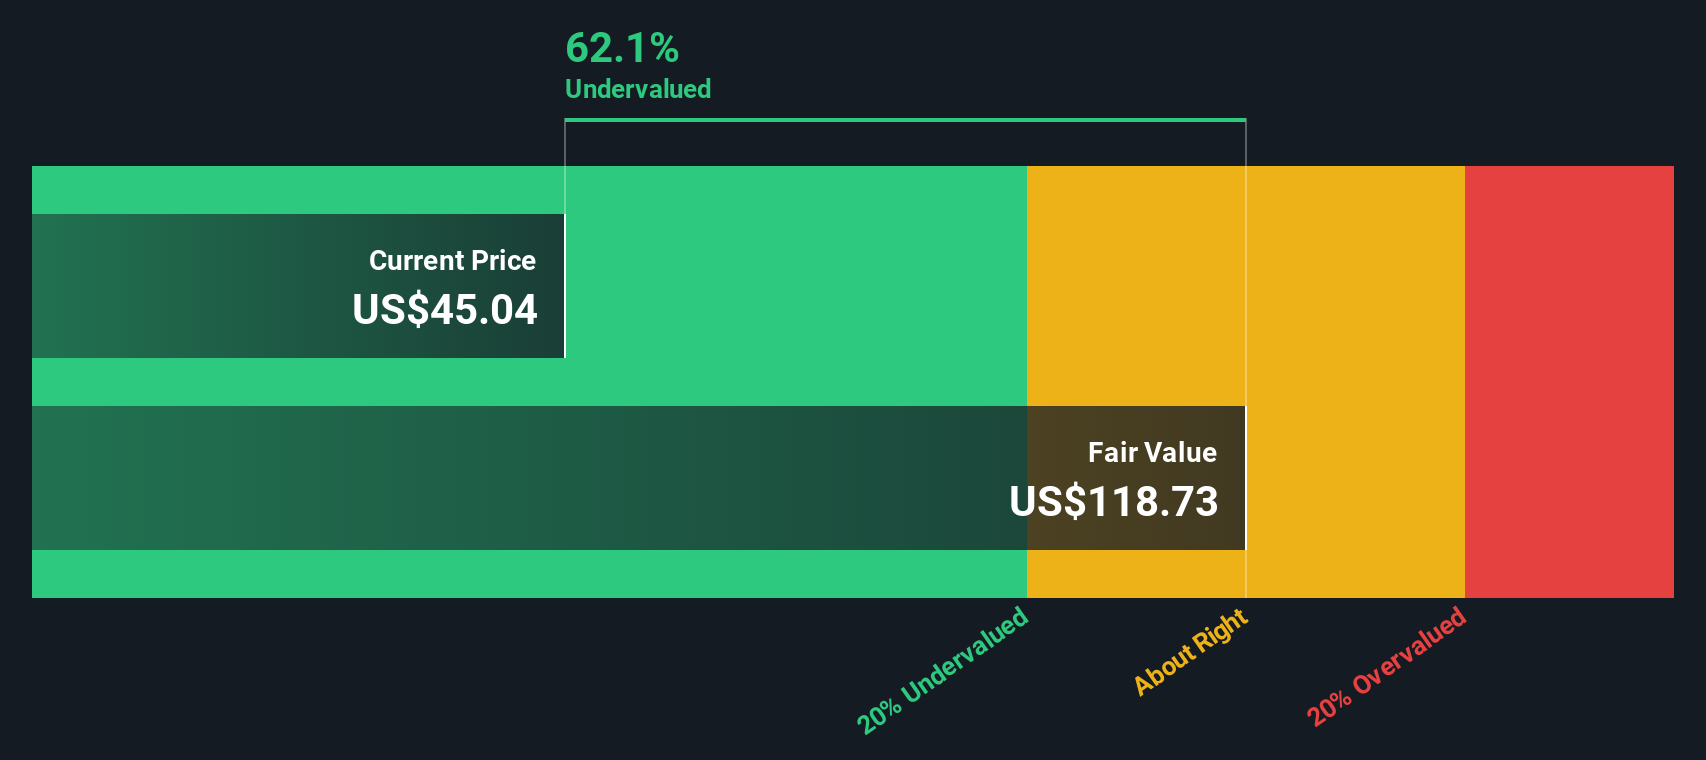
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Occidental Petroleum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 881 undervalued stocks based on their cash flows. If you save a screener we even alert you when new companies match — so you never miss a potential opportunity.
Build Your Own Occidental Petroleum Narrative
If you see the numbers differently or want to test your own assumptions, you can build a complete Occidental Petroleum story yourself in just a few minutes, starting with Do it your way.
A great starting point for your Occidental Petroleum research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
Looking for more investment ideas?
If you stop with just one stock, you risk missing other clear opportunities, so take a few minutes to scan wider and pressure test your thinking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com