
How Rising WTI Prices And Mixed Earnings At Occidental Petroleum (OXY) Have Changed Its Investment Story
- In recent months, Occidental Petroleum has seen its fortunes tied closely to rapidly rising WTI crude prices, even as its latest quarterly results showed lower revenue but adjusted earnings per share that exceeded analyst expectations.
- This combination of stronger oil prices, mixed financial performance and generally cautious analyst views is reshaping how investors weigh the company’s risk‑reward profile.
- With rising WTI crude prices as a key backdrop, we’ll now examine how these developments influence Occidental Petroleum’s broader investment narrative.
Trump’s oil boom is here — pipelines are primed to profit. Discover the 22 US stocks riding the wave.
What Is Occidental Petroleum’s Investment Narrative?
To own Occidental Petroleum today, you have to believe in an oil‑leveraged story where stronger WTI prices can offset mixed fundamentals, a high earnings multiple and a heavy balance sheet. The recent run‑up in crude and OXY’s EPS beat have clearly sharpened the near term catalyst around oil price momentum and the upcoming Q4 2025 results, but they do not fully erase concerns flagged by low profitability, a modest Return on Equity and elevated debt metrics. Analyst targets still sit only moderately above the share price, and recent “Neutral” ratings hint that expectations were already restrained before this bounce. Put simply, the latest news reinforces oil price sensitivity as the key upside trigger, while the core risks around leverage, margin pressure and valuation remain largely intact.
Occidental Petroleum’s shares have been on the rise but are still potentially undervalued. Find out how large the opportunity might be.
Exploring Other Perspectives
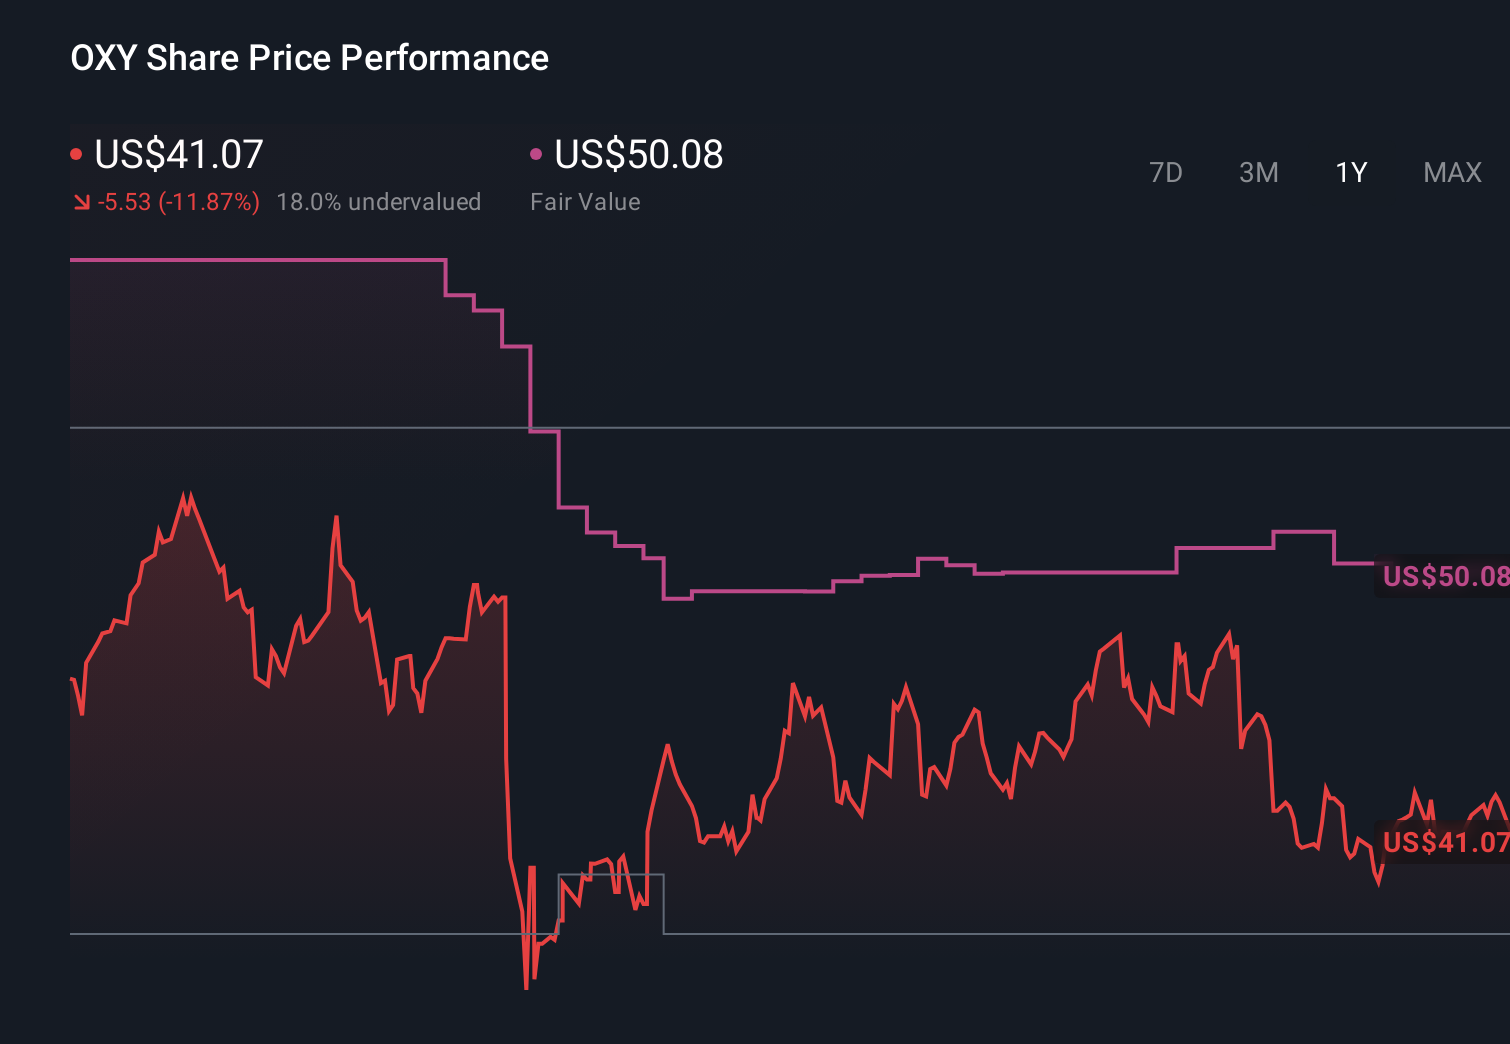
Thirty fair value estimates from the Simply Wall St Community span roughly US$29 to over US$125 per share, with many clustered in the US$40 to US$70 range. When you weigh those against the recent oil‑driven share strength and the company’s debt concerns, it is clear that different investors are focusing on very different parts of the Occidental story. This is exactly why it can pay to compare several viewpoints side by side before forming your own view.
Explore 30 other fair value estimates on Occidental Petroleum — why the stock might be worth over 2x more than the current price!
Build Your Own Occidental Petroleum Narrative
Disagree with this assessment? Create your own narrative in under 3 minutes — extraordinary investment returns rarely come from following the herd.
Ready For A Different Approach?
Our daily scans reveal stocks with breakout potential. Don’t miss this chance:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com