
Is EQT’s (EQT) Debt-Reduction Push Reshaping Its Natural Gas Export Ambitions?
- EQT recently drew increased attention as several major analysts highlighted its integrated natural gas operations, growing pipeline projects, and liquefied natural gas export agreements as key strengths in a changing energy landscape.
- An interesting angle for investors is how EQT’s focus on lowering debt alongside expanding its gas infrastructure could influence perceptions of its resilience and flexibility.
- Against this backdrop and recent share price gains, we’ll explore how EQT’s emphasis on natural gas export growth shapes its broader investment narrative.
Uncover the next big thing with financially sound penny stocks that balance risk and reward.
What Is EQT’s Investment Narrative?
To own EQT, you have to buy into natural gas as a core part of global energy supply and trust that integrated upstream, pipeline and LNG export exposure can translate into durable cash generation. The latest analyst upgrades and optimism around Q4 2025 earnings tighten the focus on a few key short term catalysts: how well upcoming results back up expectations for improved profitability, and whether ongoing debt reduction continues at the pace some are now anticipating. The recent redemption of high coupon notes and the push into export agreements both speak to that story, but they also raise the stakes if commodity prices soften or LNG volumes disappoint. With the share price already up sharply on sentiment, execution risk and gas price volatility feel more immediate than they did before this rally.
However, there is a funding and balance sheet risk here that investors should not ignore. EQT’s shares have been on the rise but are still potentially undervalued by 44%. Find out what it’s worth.
Exploring Other Perspectives
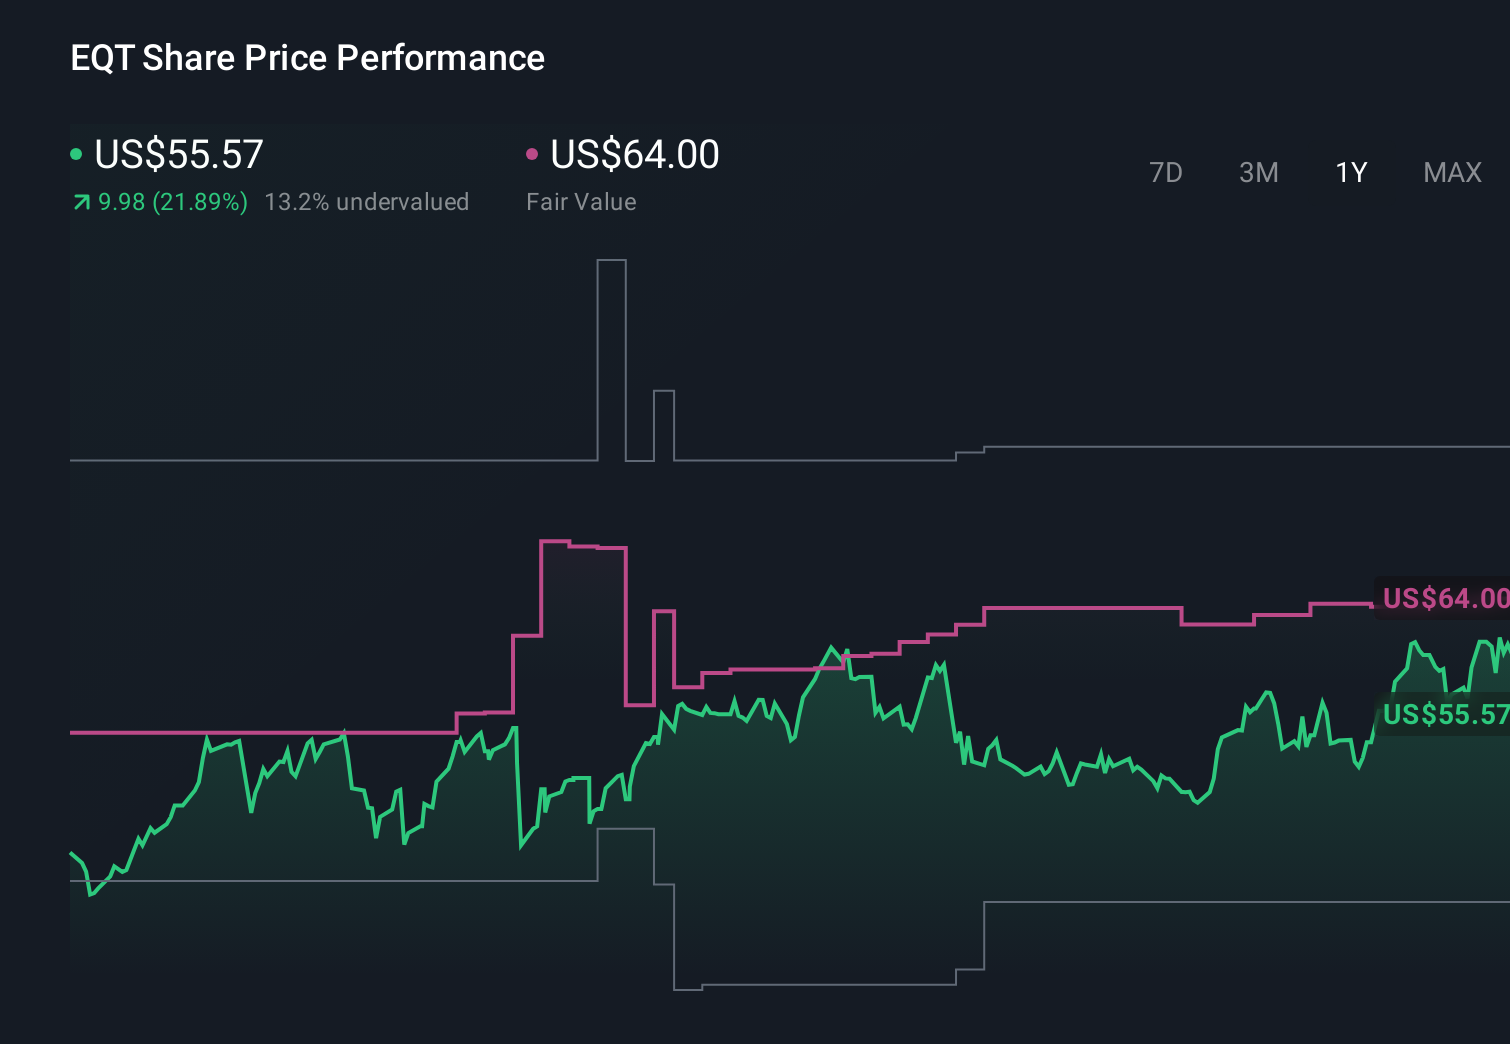
The six EQT fair value estimates from the Simply Wall St Community span roughly US$48 to just over US$101, underscoring how differently private investors see the same story. Set that wide dispersion against today’s focus on earnings expectations, debt reduction progress and LNG exports, and it becomes clear why some market participants are comfortable paying up while others are more cautious.
Explore 6 other fair value estimates on EQT — why the stock might be worth as much as 79% more than the current price!
Build Your Own EQT Narrative
Disagree with this assessment? Create your own narrative in under 3 minutes — extraordinary investment returns rarely come from following the herd.
- A great starting point for your EQT research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- Our free EQT research report provides a comprehensive fundamental analysis summarized in a single visual — the Snowflake — making it easy to evaluate EQT’s overall financial health at a glance.
Searching For A Fresh Perspective?
Don’t miss your shot at the next 10-bagger. Our latest stock picks just dropped:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if EQT might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com