
Did KKR’s (KKR) First India Climate Deal Just Redefine Its Private Markets Growth Narrative?
- Earlier this month, KKR-managed funds committed up to US$310 million to partner with Allfleet and PMI Electro, taking a majority stake in Allfleet and a minority stake in PMI Electro to help scale electric bus fleets across Indian cities.
- This marks KKR’s first Global Climate Transition investment in India, highlighting a growing emphasis on climate-focused infrastructure in high-growth emerging markets.
- Next, we’ll examine how KKR’s first Global Climate Transition investment in India could influence its long-term private markets growth story.
This technology could replace computers: discover 24 stocks that are working to make quantum computing a reality.
KKR Investment Narrative Recap
To own KKR, you need to believe in its ability to keep growing fee-based earnings across private markets while managing credit and liquidity risks in a competitive alternatives industry. The latest rumors around a potential CoolIT exit and a bid for UP Education do not materially change the near term picture, where the key catalyst remains fundraising and deployment in private credit, and the biggest risk is asset quality if riskier lending or asset-based finance underperforms.
Among recent announcements, KKR’s first Global Climate Transition investment in India, backing Allfleet and PMI Electro with up to US$310 million, is most relevant. It fits directly into the firm’s push to scale global infrastructure and energy-transition assets, a focus that could be important for sustaining fee-paying AUM growth even if more traditional buyout and private credit opportunities become harder to source.
Yet while this growth story is appealing, investors also need to be aware of the potential for earnings volatility if monetizations slow or capital markets appetite weakens…
Read the full narrative on KKR (it’s free!)
KKR’s narrative projects $13.7 billion revenue and $5.4 billion earnings by 2028. This requires a 13.9% yearly revenue decline and a $3.4 billion earnings increase from $2.0 billion today.
Uncover how KKR’s forecasts yield a $140.24 fair value, a 55% upside to its current price.
Exploring Other Perspectives
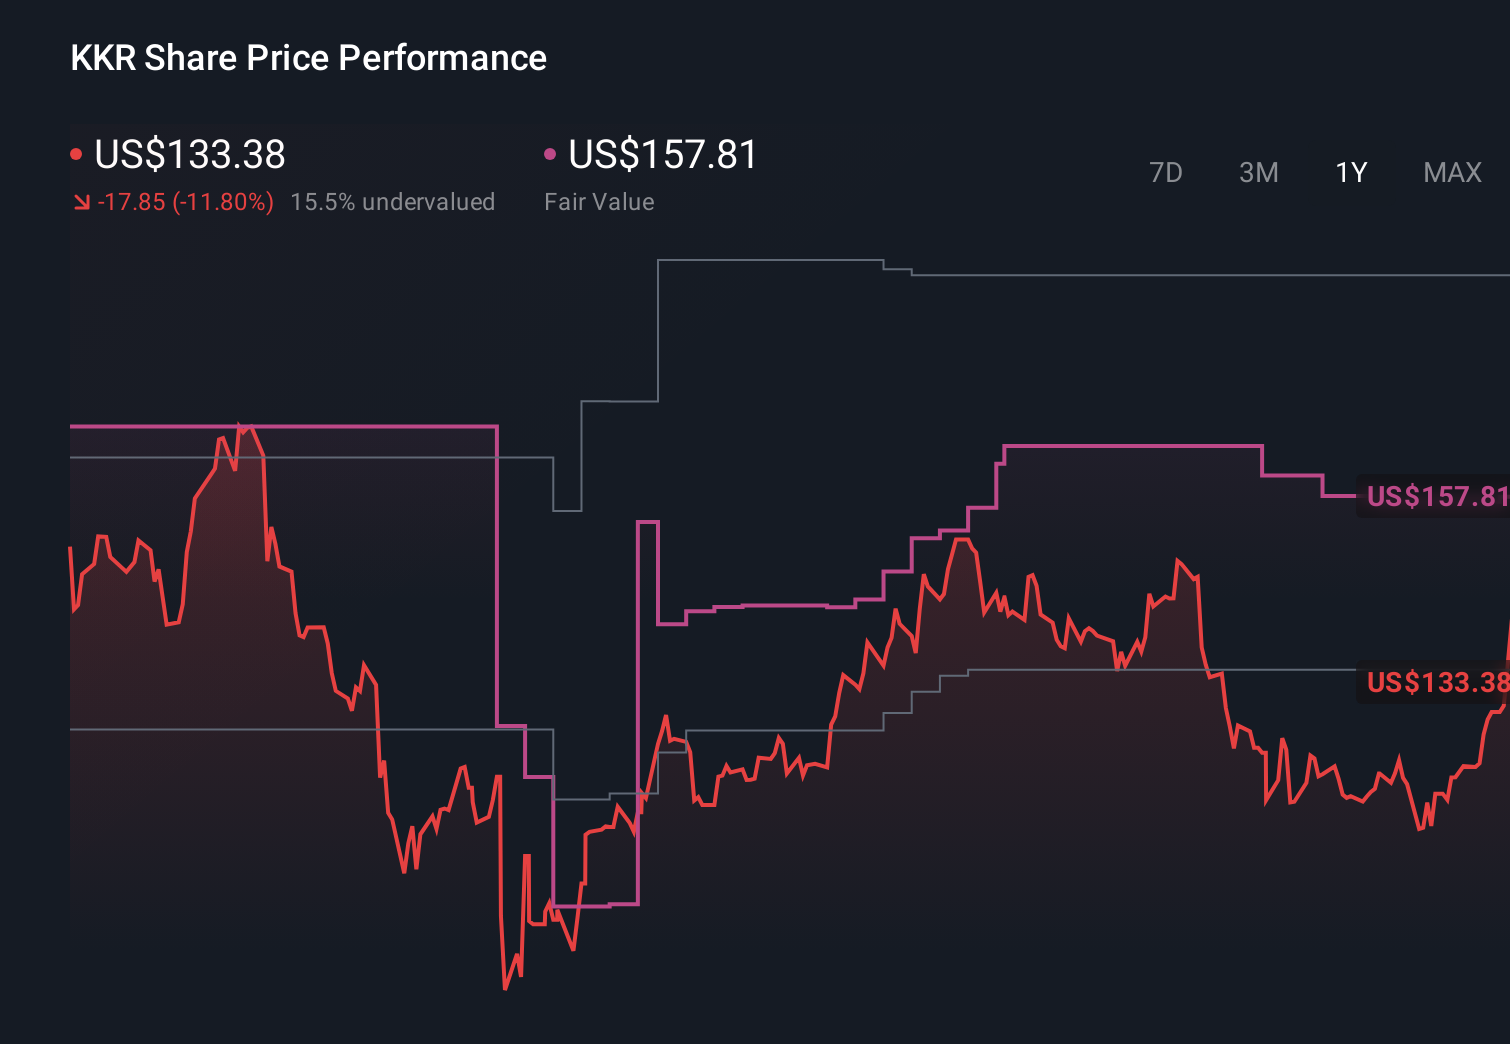
While consensus sees long term private markets growth, the most bearish analysts were assuming KKR’s revenue could fall about 24 percent annually even as earnings rose toward roughly US$5.5 billion, so this new India climate deal and the Global Atlantic growth story may ultimately shift how pessimistic or optimistic those forecasts look.
Explore 8 other fair value estimates on KKR — why the stock might be worth less than half the current price!
Form Your Own Verdict
Don’t just follow the ticker — dig into the data and build a conviction that’s truly your own.
- A great starting point for your KKR research is our analysis highlighting 2 key rewards that could impact your investment decision.
- Our free KKR research report provides a comprehensive fundamental analysis summarized in a single visual — the Snowflake — making it easy to evaluate KKR’s overall financial health at a glance.
Seeking Other Investments?
Don’t miss your shot at the next 10-bagger. Our latest stock picks just dropped:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if KKR might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com