
The Bull Case For Occidental Petroleum (OXY) Could Change Following OxyChem Sale and Q3 2025 Earnings Results
- Occidental Petroleum recently reported third-quarter 2025 results, revealing a year-over-year decline in revenue and net income despite production exceeding guidance at 1,465 thousand barrels of oil equivalent per day.
- An important development from the past quarter was the completed US$9.7 billion sale of its OxyChem business to Berkshire Hathaway, aimed at reducing debt and improving annual interest expenses by US$350 million.
- We’ll explore how Occidental’s increased production and efforts to improve the balance sheet may influence its longer-term investment outlook.
AI is about to change healthcare. These 32 stocks are working on everything from early diagnostics to drug discovery. The best part — they are all under $10b in market cap — there’s still time to get in early.
Occidental Petroleum Investment Narrative Recap
To invest in Occidental Petroleum today, you have to believe that global oil and gas demand will remain resilient enough to support the company’s cost structure, even as energy transition pressures persist. Recent news including the completed US$9.7 billion OxyChem sale may help improve Occidental’s balance sheet, but it does not materially change the immediate risk tied to oil price volatility, which still dominates the near-term outlook.
Among recent announcements, Occidental’s affirmation of its quarterly dividend at US$0.24 per share stands out for investors seeking signs of capital returns. While dividend continuity may reassure some, it should be considered in the context of Occidental’s ongoing efforts to manage leverage and respond to fluctuations in operating earnings.
Yet, despite higher production, investors should be aware that persistent oil price swings could continue to challenge Occidental’s core business…
Read the full narrative on Occidental Petroleum (it’s free!)
Occidental Petroleum’s outlook anticipates $29.0 billion in revenue and $3.7 billion in earnings by 2028. This scenario is based on a 2.2% annual revenue growth and a $2.0 billion increase in earnings from the current $1.7 billion.
Uncover how Occidental Petroleum’s forecasts yield a $49.91 fair value, a 19% upside to its current price.
Exploring Other Perspectives
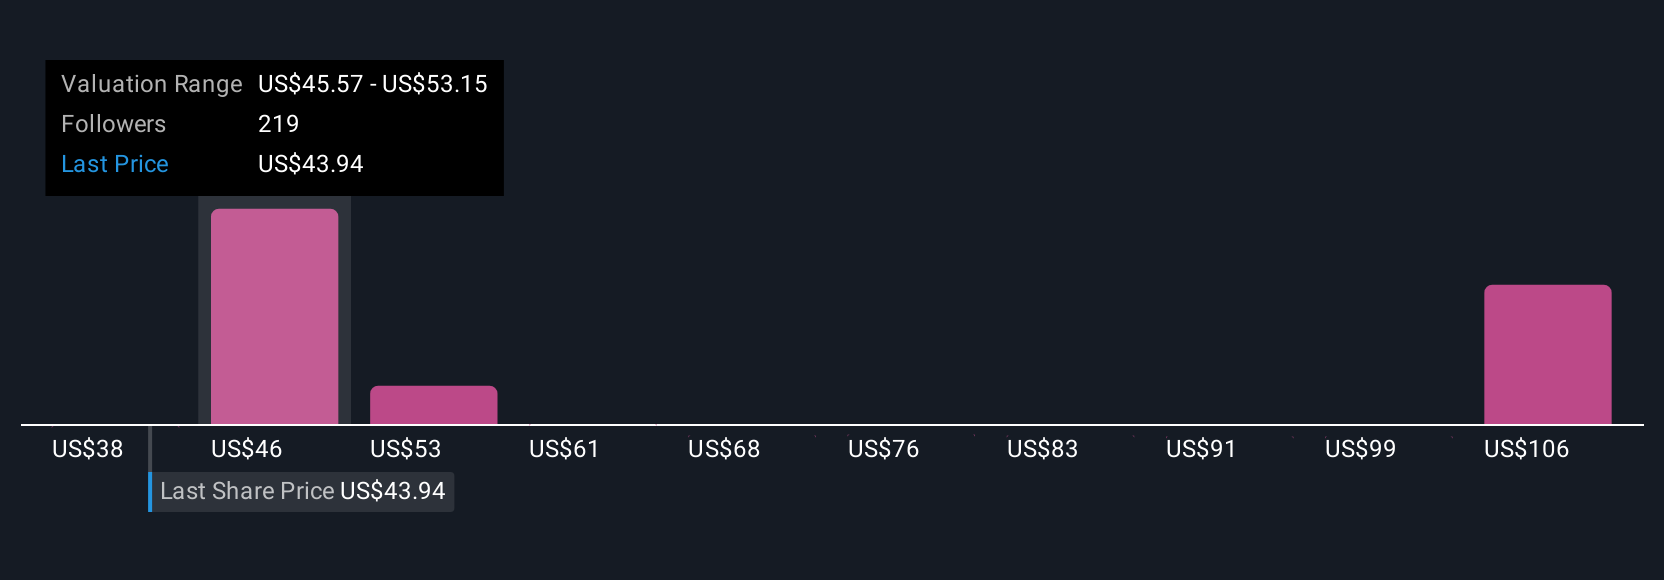
Simply Wall St Community members shared 26 fair value estimates for Occidental, ranging from US$31.19 to US$66.74 per share. While opinions vary widely, keep in mind that oil price swings still represent a key factor for future performance.
Explore 26 other fair value estimates on Occidental Petroleum — why the stock might be worth 25% less than the current price!
Build Your Own Occidental Petroleum Narrative
Disagree with existing narratives? Create your own in under 3 minutes — extraordinary investment returns rarely come from following the herd.
No Opportunity In Occidental Petroleum?
These stocks are moving-our analysis flagged them today. Act fast before the price catches up:
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com